
Do investors price stocks based mostly on rational analysis or feelings? In their February 2008 paper entitled “Affect in a Behavioral Asset Pricing Model”, Meir Statman, Kenneth Fisher and Deniz Anginer use survey results to investigate both the objective and subjective (perceived) connections between risk and return. Using results of: (1) the 1982-2006 annual Fortune surveys of senior executives, directors and security analysts regarding the long-term investment value of companies; and (2) May and July 2007 surveys of high-net worth clients of a large investment firm, they conclude that:
- Investors prefer stocks with positive images, and these preferences boost the prices and depress the future returns of such stocks. The mean annualized return of a portfolio of stocks deemed Admired (Despised) by Fortune survey respondents, rebalanced every four years during
1982-2006, is 15.1% (19.7%). - The Fortune survey Despised stocks have on average higher objective risk than Admired stocks: higher betas, lower market capitalizations, higher book-to-market values and lower short-term momentum. Despised stocks also tend to have higher earnings-to-price ratios, higher cash flow-to-price ratios, lower past sales and earnings growth rates and lower returns on assets. In other words, stocks with higher returns tend to carry higher objective risks.
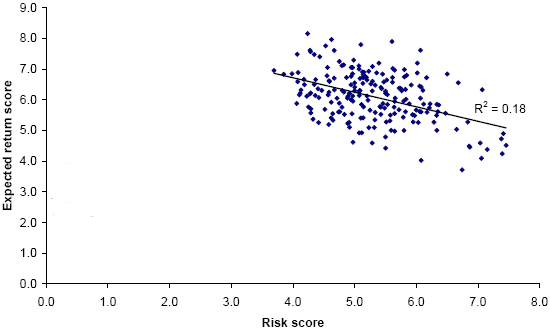
- However, separate surveys of high-net worth investors yield a negative correlation between subjective (perceived) risk and expected return for a large subset of the Fortune survey companies. (See the figure below.) This negative correlation suggests that investors rely more on emotion than reason in assessing the risk-return relationship.
- Market capitalization and book-to-market ratio relate positively to emotional response (investors tend to have more positive attitudes toward large growth than small value) and may be proxies for it.
The following chart, taken from the paper, relates the mean relative expected return and perceived risk (both on ten-point scales) of 210 stocks, as determined by surveys of high-net worth investors. The resulting negative correlation (high return scores correspond to low risk scores) indicates that investors view the risk-return relationship emotionally rather than rationally per the Capital Asset Pricing Model. They see stocks that elicit positive (negative, or less positive) emotions as offering both high (low) future returns and low (high) future risk.
 In summary, investors on the whole base their (mis)perceptions of risk and return on feelings rather than rational pricing analysis. Contrarians may be able to exploit the underpricing of “despised” stocks by focusing on small value.
Frequently Asked Questions
What is the affect heuristic in asset pricing?
The affect heuristic in asset pricing is the tendency of investors to judge stocks by the feelings they evoke rather than by objective analysis. In the Statman, Fisher and Anginer (2008) behavioral asset pricing framework, investors prefer stocks with positive images, which boosts their prices and depresses their future returns.
Do stocks that investors despise outperform stocks that investors admire?
Despised stocks outperformed Admired stocks in the Fortune survey-based portfolios, with a mean annualized return of 19.7% versus 15.1%. The portfolios were rebalanced every four years over 1982-2006. The authors conclude that preferences for stocks with positive images boost their prices and depress their future returns.
How do researchers measure investor emotion and perceived risk toward stocks?
Researchers measured investor emotion and perceived risk using surveys. They used the 1982-2006 annual Fortune surveys of executives, directors and analysts on companies' long-term investment value, plus May and July 2007 surveys of high-net-worth clients of a large investment firm. The client surveys rated relative expected return and perceived risk on ten-point scales for 210 stocks.
How does the behavioral view of risk and return differ from the Capital Asset Pricing Model?
The behavioral view differs from the Capital Asset Pricing Model (CAPM) in that investors perceive a negative relationship between risk and expected return, while CAPM implies a positive one. In the high-net-worth surveys, stocks that evoked positive emotions were seen as offering both high returns and low risk. The authors conclude that investors rely on feelings rather than rational pricing analysis, although objectively riskier Despised stocks (higher betas, smaller capitalizations, higher book-to-market values) did earn higher returns.
What are the limitations of using surveys of admired and despised stocks to find mispricing?
The findings rest on survey-based measures, and the paper's perceived risk and return results come from surveys of high-net-worth clients of a single large investment firm in 2007. The Despised stocks also carried higher objective risks, such as higher betas and book-to-market values and lower market capitalizations, so their higher returns may partly reflect compensation for risk. Market capitalization and book-to-market ratio relate to emotional response and may be proxies for it, which makes emotion hard to separate from known risk factors.