
We have selected for retrospective review a few all-time “best selling” research papers of the past few years from the General Financial Markets category of the Social Science Research Network (SSRN). Here we summarize the March 1998 paper entitled “The Dow Theory: William Peter Hamilton’s Track Record Re-Considered” (download count nearly 5,900) by Stephen Brown, William Goetzmann and Alok Kumar. This research applies risk adjustment and out-of-sample testing to re-examine Alfred Cowles’ 1934 debunking of the Dow Theory (as defined by the 255 editorials of William Peter Hamilton in The Wall Street Journal during 1902-1929). They conclude that:
- Hamilton was right about the short-term direction of the stock market about 60% of the time. His accuracy rate was higher during bear markets than during bull markets.
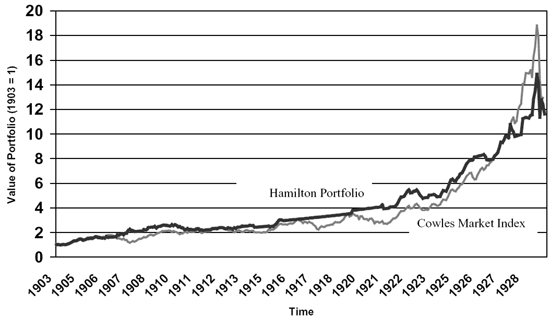
- Hamilton’s (Dow Theory) timing approach produces high Sharpe ratios and positive alphas during 1902-1929. This result counters Cowles’ 1934 analysis, which did not include risk adjustment. Adjustment for risk appears to vindicate Dow Theory. (See chart below.)
- Since 1929, the Dow Theory appears to have some predictive power, but trading frictions preclude large excess returns, especially since the 1970s. The theory has continued to offer reduced portfolio volatility. The faster the execution of the theory’s trading signals, the better its returns.
- Dow Theory, as articulated by Hamilton, is a trend (momentum) strategy.
The following chart, extracted from the paper, compares the performance of a Dow Theory-driven (Hamilton) portfolio with that of the broad market (Cowles Market Index) during 1902-1929. The chart shows that Dow Theory dampened volatility and even provided higher raw returns over significant periods, especially periods with downturns.
The paper also provides a concise description and early history of the Dow Theory, including Cowles’ 1934 analysis. One of the theory’s fundamental axioms, in Hamilton’s own words, is: “Prosperity will drive men to excess, and repentance for the consequences of those excesses will produce a corresponding depression.” There is a never-ending cycle of irrational optimism and irrational pessimism.
In summary, the Dow Theory has generated excess risk-adjusted (but not raw) returns when compared to buy-and-hold over some significant periods by following large trends.
Frequently Asked Questions
What is Dow Theory in stock market investing?
Dow Theory is a trend-following (momentum) approach to timing the stock market, as articulated by William Peter Hamilton in his 255 Wall Street Journal editorials from 1902 to 1929. It rests on the axiom that prosperity drives excess and the repentance for those excesses produces depression, creating a never-ending cycle of irrational optimism and pessimism.
Does Dow Theory actually work for timing the stock market?
Dow Theory produced high Sharpe ratios and positive alphas during 1902-1929, with Hamilton correctly calling the short-term market direction about 60% of the time. It generated excess risk-adjusted (but not raw) returns versus buy-and-hold over some significant periods by following large trends. Since 1929 it shows some predictive power, but trading frictions preclude large excess returns, especially since the 1970s.
How do researchers test whether Dow Theory beats buy-and-hold?
Brown, Goetzmann and Kumar tested Dow Theory by applying risk adjustment and out-of-sample testing to the trading signals from Hamilton's 255 Wall Street Journal editorials during 1902-1929. They compared the resulting Hamilton portfolio against the broad market (Cowles Market Index) using Sharpe ratios and alphas. Results were also sensitive to execution speed, as faster execution of signals produced better returns.
How does the Dow Theory's performance compare to the Cowles 1934 conclusion and a buy-and-hold strategy?
Alfred Cowles' 1934 analysis debunked Dow Theory, but it did not adjust for risk, whereas the later risk-adjusted analysis appears to vindicate it. Compared with buy-and-hold, Dow Theory dampened volatility and provided higher raw returns over some significant periods, especially during downturns. Overall, it generated excess risk-adjusted returns but not excess raw returns.
What are the limitations of using Dow Theory today?
Since 1929, trading frictions have prevented Dow Theory from delivering large excess returns, especially since the 1970s, even though it still appears to have some predictive power. Its main continuing benefit is reduced portfolio volatility rather than higher raw returns. Its returns also depend on fast execution of signals, and Hamilton's accuracy was higher in bear markets than in bull markets.