
Reader Mike Korell of ChartsEdge suggested an evaluation of his own S&P 500 Index forecasts for inclusion in Gurus. These “stock market forecasts are based on cycle data which has been analyzed by a Pattern Recognition Program. This use of artificial intelligence reduces the effect of personal bias and allows the simultaneous cycle analysis of many input variables.” To construct a statistical evaluation, we focus on the open and close levels of the ChartsEdge weekly forecasts, apparently issued on Sundays. Using estimates of the forecasted S&P 500 Index open and close levels from inspection of the ChartsEdge weekly charts and actual contemporaneous S&P 500 Index weekly open and close data for weeks beginning 9/8/08 through 9/7/10 (104 weekly returns), we find that:
Over the entire sample period, the average weekly ChartsEdge forecasted (actual) S&P 500 Index return is +0.05% (-0.04%), with standard deviation of weekly returns 2.80% (4.15%), so forecasted weekly returns tend to be higher and less volatile than actual weekly returns.
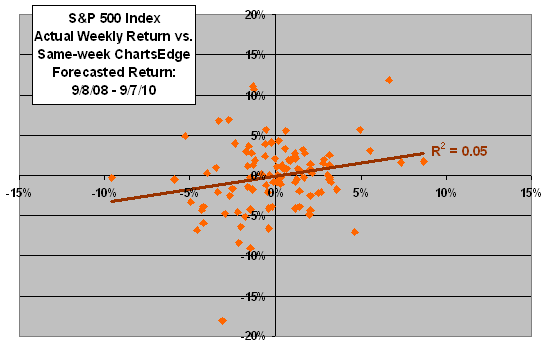
The following scatter plot relates actual weekly S&P 500 Index returnto the same-week forecasted returns over the entire sample period. The Pearson correlation between the two series is 0.22 and the R-squared statistic is 0.05, indicating that forecasted returns explain 5% (one twentieth) of actual weekly returns.
Removing the two observations corresponding to the single largest weekly loss (-18.1% the week of 10/6/08) and the single largest weekly gain (+11.9% the week of 11/24/08) of the index reduces the explanatory power of the forecasts from 5% to 2%. In other words, just a few additional realistically extreme observations could substantially change predictive power statistics.
Observations in the upper right and lower left quadrants represent forecasts in the correct direction (59% of all observations). However, a few of the correct and incorrect directional forecasts correspond to immaterially small actual returns (comparable to reasonable trading frictions).
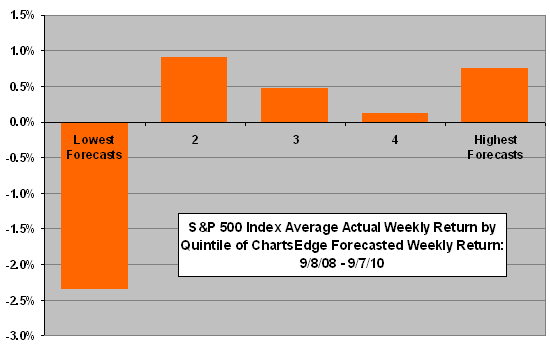
To investigate non-linearity in the relationship, we consider average actual returns by forecast quintile.
The next chart shows the average return by quintile (fifth) of forecasted weekly returns, sorted from lowest to highest, over the entire sample period. Results are not systematic across quintiles and suggest that the above predictive power of the forecasts derives mostly from the lowest (most negative) forecasts. In fact, removing the 22 lowest forecasts (roughly the lowest quintile) reduces the R-squared statistic for the relationship to 0.00. In other words, only forecasts of substantially negative returns appear to exhibit predictive power.
The success of a trading strategy based on the ChartsEdge weekly forecasted open and close therefore may depend critically on the frequency of large weekly declines in the sample period.
The sample is small for this kind of analysis (only 20-21 observations per quintile).
Note that the historical charts were not public until 9/12/10 (as a condition of evaluation). CXOadvisory.com reviews only publicly available forecasts/trading records to: (1) avoid risks of exposing proprietary data; (2) allow subscribers of reviewed services to verify that records are as issued; and, (3) allow CXOadvisory.com readers to check data and calculations. Note also that the forecast for the week beginning 1/11/10 is missing.
In summary, results from simple tests suggest that the ChartsEdge forecasts of weekly returns (open to close) may have some power to forecast bad weeks for the S&P 500 Index.
Using higher frequency data from the prediction charts (daily or intraday) may produce different results. Typically, higher frequency predictions are less accurate than lower frequency predictions because the noise to signal ratio in financial market returns increases as measurement interval decreases. Note that testing multiple intervals on the same set of data introduces data snooping bias.
Because this statistical, highly quantitative evaluation is markedly different in approach from the more qualitative assessments summarized in Gurus, it is not included in that summary.
Frequently Asked Questions
What are ChartsEdge weekly S&P 500 forecasts and how are they generated?
ChartsEdge weekly forecasts are S&P 500 Index open and close level predictions based on cycle data analyzed by a Pattern Recognition Program, an artificial intelligence tool intended to reduce personal bias. The program simultaneously analyzes cycles across many input variables. The forecasts appear to be issued on Sundays for the coming week.
Do ChartsEdge forecasts predict weekly S&P 500 returns?
ChartsEdge forecasts show weak predictive power for weekly S&P 500 returns, with an R-squared of 0.05 and a Pearson correlation of 0.22 over 104 weeks (September 2008 to September 2010). Forecasts pointed in the correct direction in 59% of weeks. The predictive power appears limited to forecasting bad weeks, since removing the 22 lowest forecasts drops R-squared to 0.00.
How do you test the accuracy of weekly stock market forecasts against actual S&P 500 returns?
The ChartsEdge evaluation compared forecasted weekly open-to-close S&P 500 returns, estimated by inspecting the forecast charts, with actual weekly open-to-close returns for 104 weeks starting 9/8/08. It used the Pearson correlation, R-squared, directional accuracy by scatter-plot quadrant, and average actual returns by forecast quintile to check for non-linearity. Robustness checks included removing the largest weekly gain and loss and removing the lowest forecasts.
How do forecasted weekly S&P 500 returns compare with actual returns in terms of average and volatility?
ChartsEdge forecasted weekly S&P 500 returns averaged +0.05%, versus an actual average of -0.04%. Forecasted returns were also less volatile, with a standard deviation of 2.80% against 4.15% for actual weekly returns. Forecasts therefore tended to be higher and smoother than what the index actually delivered over the 104-week sample.
What are the limitations of evaluating stock market forecasts with a small sample like this?
The ChartsEdge evaluation has limited reliability because the sample is small, with only 20-21 observations per quintile, and removing the single largest weekly loss (-18.1%) and gain (+11.9%) cut R-squared from 5% to 2%. Results may depend heavily on how often large weekly declines occurred in the sample period. Other caveats include forecast values estimated from charts, one missing week (1/11/10), and data snooping bias if multiple intervals such as daily or intraday data are tested on the same data.