
Do stock indexes behave predictably after extreme price levels, such as 52-week highs and 52-week lows? To investigate, we consider the behaviors of the Dow Jones Industrial Average (DJIA), the S&P 500 Index and the NASDAQ Composite Index over the 13 weeks after 52-week highs and lows during their available histories. Using weekly levels of these indexes from October 1928, January 1950 and February 1971, respectively, through January 2013, we find that:
Over the respective available sample periods:
- DJIA has 707 52-week highs and 192 52-week lows (ratio 3.7:1).
- The S&P 500 Index has 591 52-week highs and 129 52-week lows (ratio 4.6:1).
- The NASDAQ Composite Index has 389 52-week highs and 105 52-week lows (ratio 3.7:1).
Highs (lows) tend to cluster during bull (bear) markets.
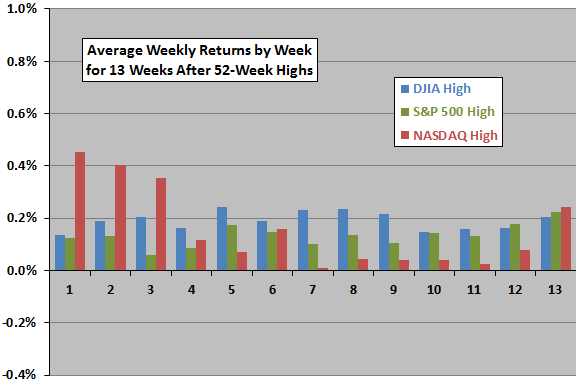
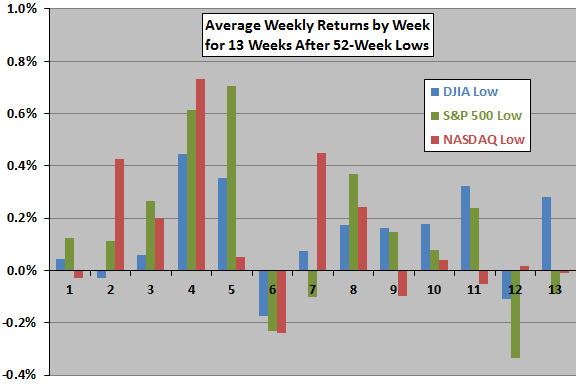
The following two charts summarize average returns by week for 13 weeks after 52-week highs (upper chart) and 52-week lows (lower chart) over the available sample periods. The average weekly returns for DJIA, the S&P 500 Index and the NASDAQ Composite Index over these sample periods are 0.12%, 0.16% and 0.20%, respectively.
Results indicate that weekly returns during the quarter after 52-week highs (lows) tend to be positive and placid (volatile with an initial reversal).
For a different perspective, we look at standard deviations of weekly returns.
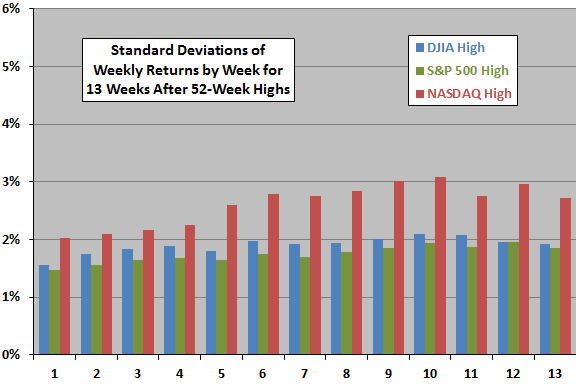
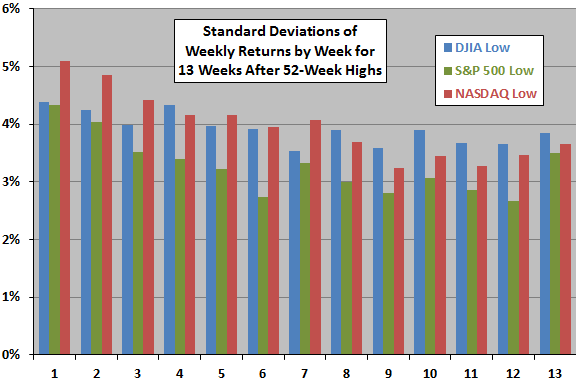
The next two charts summarize standard deviations of weekly returns by week for 13 weeks after 52-week highs (upper chart) and 52-week lows (lower chart) over the available sample periods. The standard deviations of all weekly returns for DJIA, the S&P 500 Index and the NASDAQ Composite Index over these sample periods are 2.47%, 2.08% and 2.79%, respectively.
Results indicate that indexes tend to exhibit low but rising (high but falling) volatility during the quarter after 52-week highs (lows).
How do the average returns by week translate into cumulative returns?
The final three charts summarize average cumulative returns during the 13 weeks after 52-week highs and lows for DJIA (upper chart), the S&P 500 Index (middle chart) and the NASDAQ Composite Index (lower chart) over the available sample periods. For comparison, each chart includes the trend based on average weekly return over the available sample period for the applicable index.
Results are inconsistent across indexes/sample periods, undermining belief in predictable equity market behavior after index 52-week highs and lows.
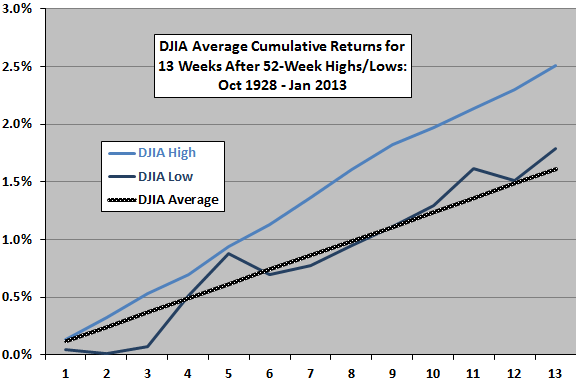
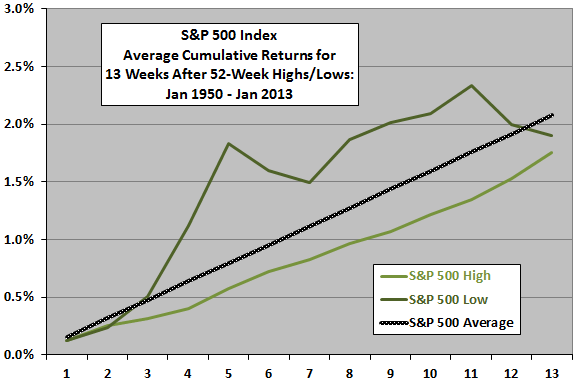
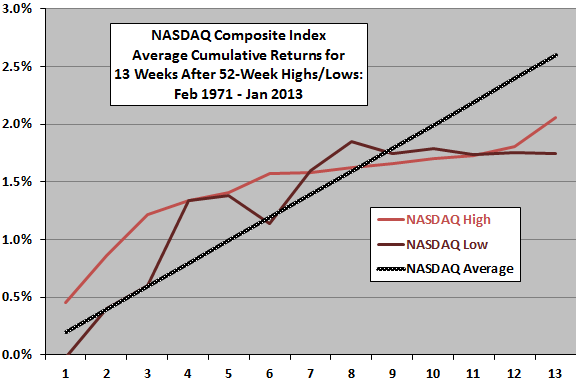
In summary, evidence from simple tests on three indexes indicates that equity markets tend to be relatively placid (volatile) during the quarter after 52-week highs (lows), with cumulative performances inconsistent across indexes/sample periods.
Cautions regarding findings include:
- As noted, sample periods differ across indexes.
- Clustering of 52-week highs and lows, such that subsequent 13-week return measurement intervals overlap, may distort cumulative return statistics. From a practical perspective, all observations are not independently tradable.
Frequently Asked Questions
What is a 52-week high or 52-week low for a stock index?
A 52-week high (low) for a stock index is a weekly level that is the highest (lowest) reached over the prior 52 weeks. In the study of the DJIA, S&P 500 and NASDAQ Composite, highs tend to cluster during bull markets and lows during bear markets. Over their available histories, the DJIA had 707 highs and 192 lows, the S&P 500 had 591 highs and 129 lows, and the NASDAQ Composite had 389 highs and 105 lows.
Do stock indexes behave predictably after hitting 52-week highs or lows?
Stock indexes show only partly predictable behavior after 52-week highs and lows: volatility patterns are fairly consistent, but cumulative returns are not. Over the 13 weeks after highs, weekly returns tend to be positive and placid, while after lows they tend to be volatile with an initial reversal. Cumulative 13-week returns were inconsistent across the DJIA, S&P 500 and NASDAQ Composite and across sample periods, undermining belief in predictable market behavior.
How do you test stock index returns in the weeks after a 52-week high or low?
Stock index returns after 52-week highs and lows were tested by identifying each weekly 52-week high and low, then averaging returns and standard deviations of returns for each of the following 13 weeks. The study used weekly levels of the DJIA from October 1928, the S&P 500 from January 1950 and the NASDAQ Composite from February 1971, through January 2013. Average cumulative returns were then compared against the trend implied by each index's average weekly return over its sample period (0.12% for DJIA, 0.16% for S&P 500, 0.20% for NASDAQ).
How does stock market volatility after a 52-week high compare with volatility after a 52-week low?
Stock index volatility after a 52-week high tends to be low but rising, while volatility after a 52-week low tends to be high but falling, over the following 13 weeks. For reference, standard deviations of all weekly returns over the sample periods were 2.47% for the DJIA, 2.08% for the S&P 500 and 2.79% for the NASDAQ Composite. Weekly returns after highs tend to be positive and placid, versus volatile with an initial reversal after lows.
What are the limitations of using 52-week highs and lows to predict stock index returns?
Using 52-week highs and lows to predict stock index returns has several limitations: sample periods differ across the three indexes, and 13-week cumulative results were inconsistent across them. Because highs and lows cluster, the subsequent 13-week measurement windows overlap, which may distort cumulative return statistics. From a practical perspective, not all observations are independently tradable.