
Does the term structure of the the option-implied expected volatility of the S&P 500 Index (VIX, normally measured at a one-month horizon) predict future returns of variance assets such as variance swaps, VIX futures and S&P 500 Index option straddles? In his January 2015 paper entitled “Risk Premia and the VIX Term Structure”, Travis Johnson investigates the relationship between the VIX term structure slope and the variance risk premium as measured by future returns of such assets. He constructs the VIX term structure by each day calculating six values of VIX from prices of S&P 500 Index options with maturities of one, two, three, six, nine and 12 months. He measures the variance risk premium from daily returns of S&P 500 Index variance swaps, VIX futures and S&P 500 Index option straddles of various maturities. Using daily closing quotes for the specified S&P 500 index options and daily returns for the specified variance assets as available during 1996 through 2013, he finds that:
- The slope of the VIX term structure is on average positive (upward from left to right).
- The VIX term structure does not predict changes in VIX level.
- However, the VIX term structure slope predicts excess returns (relative to the risk-free rate) of S&P 500 Index variance swaps, VIX futures and S&P 500 Index option straddles for all maturities. A relatively low (high) slope predicts relatively high (low) returns.
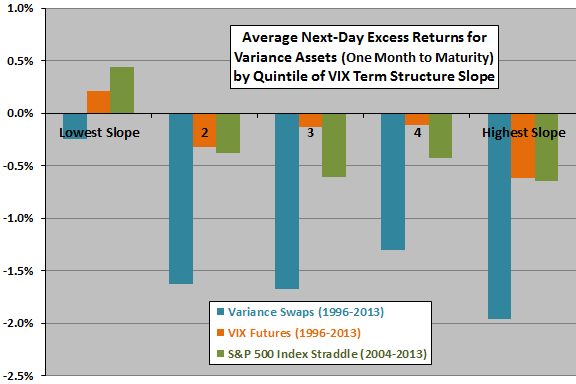
- The difference in average next-day returns between the fifths (quintiles) of days with the lowest and highest VIX term structure slopes ranges from 0.29% to 1.81% across 18 variance asset/maturity combinations (see the chart below for one-month maturity).
- When the VIX term structure slope is very low, average next-day returns become positive for 17 of these 18 combinations.
- The VIX term structure slope and implied minus expected S&P 500 Index variance are the strongest of variance risk premium predictors tested.
The following chart, constructed from data in the paper, summarizes average next-day excess returns for one-month S&P 500 Index variance swaps, one-month VIX futures and one-month S&P 500 Index option straddles as available during 1996 through 2013 across quintiles of the daily VIX term structure slope. When the VIX term structure slope is very low (very high), the term structure slopes downward (upward). Results indicate that returns generally, but not always, decrease as the VIX term structure slope increases.
In summary, evidence indicates that investors may be able to exploit information in the daily VIX term structure slope by taking positions in S&P 500 Index variance swaps, VIX futures (or derivative exchange-traded products) and S&P 500 Index option straddles.
Cautions regarding findings include:
- Timely generation of the VIX term structure may be problematic for many investors, or costly if delegated.
- Reported returns are gross, not net. Including trading frictions for variance assets would reduce these returns. These frictions may be high.
- Trading strategies based on daily VIX term structure signals may be very volatile.
- Some trades may not be directly accessible to some investors.
See also the somewhat related “Identifying VXX/XIV Tendencies” and “Exploiting VIX Futures Roll Return with ETNs”.
Frequently Asked Questions
What is the VIX term structure slope?
The VIX term structure slope describes how option-implied S&P 500 Index volatility differs across maturities, based on VIX values calculated for one, two, three, six, nine and 12 months. A downward slope means short-term implied volatility exceeds long-term, while an upward slope means the opposite. During 1996-2013 the slope was on average positive (upward).
Does the VIX term structure slope predict returns on variance swaps, VIX futures and straddles?
The VIX term structure slope does predict excess next-day returns of S&P 500 variance swaps, VIX futures and option straddles at all maturities tested, with low slopes predicting high returns and high slopes predicting low returns. During 1996-2013, the difference in average next-day returns between the lowest and highest slope quintiles ranged from 0.29% to 1.81% across 18 asset/maturity combinations. Returns were positive for 17 of 18 combinations when the slope was very low.
How is the VIX term structure built and tested against variance asset returns?
The VIX term structure is built each day by calculating six VIX values from S&P 500 Index option prices with maturities of one, two, three, six, nine and 12 months. The slope is then sorted into quintiles and compared with next-day excess returns (relative to the risk-free rate) of variance swaps, VIX futures and S&P 500 option straddles of various maturities. The test used daily data from 1996 through 2013.
Does the VIX term structure slope predict changes in VIX itself, or only the variance risk premium?
The VIX term structure slope does not predict changes in the VIX level, but it does predict variance risk premium as measured by returns of variance assets. Among the variance risk premium predictors tested, the slope and implied minus expected S&P 500 variance were the strongest. This indicates the slope's information relates to compensation for bearing variance risk rather than to the direction of VIX.
What are the limitations of trading on the VIX term structure slope?
Trading on the VIX term structure slope faces the caveat that the reported returns are gross, not net, so trading frictions, which may be high, would reduce them. Generating the term structure on a timely basis may be problematic or costly for many investors, and daily-signal strategies may be very volatile. Some of the trades may also not be directly accessible to some investors, and returns decrease with slope generally but not always.