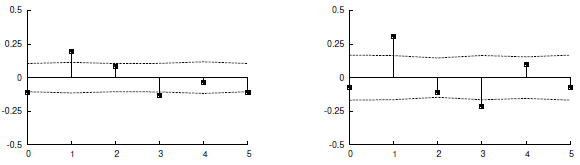
VIX exhibits day-of-week patterns with Monday elevation and Wednesday/Friday depression, showing U-shaped weekly changes after outlier control (2004-2008; S&P 500 shows no significant weekly effects).
Does the S&P 500 implied volatility index (VIX) exhibit systematic behaviors by day of the week? In their February 2012 paper entitled “Day of the Week Effect on the VIX: A Parsimonious Representation”, Maria Gonzalez-Perez and David Guerrero apply methodologies that minimize sensitivity to outliers to examine VIX day-of-the-week patterns. Using daily closes of VIX and the S&P 500 Index during 2004 through 2008, they find that:
VIX tends to be elevated on Monday and depressed on Wednesday and Friday.
VIX tends to rise on Monday.
After controlling for outliers, changes in VIX exhibit a roughly U-shaped weekly pattern, rising on Monday, falling on Tuesday and Wednesday, rising on Thursday and holding steady on Friday.
The S&P 500 Index exhibits no significant day-of-the-week effect.
The following charts, taken from the paper, summarize VIX daily level tendencies (left chart) and daily change tendencies (right chart) over the entire sample period without controlling for outliers. Days 1-5 represent Monday-Friday. The principal effect of controlling for outliers is to expose a more pronounced U-shaped pattern in VIX change tendencies (right chart).
In summary, evidence from sophisticated pattern detection tests on five years of data exposes some day-of-the week effects for VIX (with Monday most unsual), but not for the S&P 500 Index.
Cautions regarding findings include:
A sample of five years may not encompass the range of equity market conditions relevant to findings.
The authors speculate that findings are exploitable, but they address neither methods nor costs of exploitation.
It is not obvious that controlling for outliers translates to realistic exploitation.
Bitcoin Day-of-the-Week Effects? PremiumBitcoin average daily returns differ by day of week, with Monday strongest and Sunday, Tuesday and Thursday weakest, but differences are small relative to…
Momentum Based on Day of Week PremiumSame-Weekday Momentum (daily-reformed, value-weighted decile hedge on past same-weekday returns) generated 2.05% average gross monthly return vs 1.28% for Standard Momentum (U.S. stocks, 1963-2021;…
SPY by Day of the Week and OvernightFreeSPY overnight returns exceed intraday returns on average but effect is unstable across subperiods (Jan 1993-Aug 2017; close-open vs open-close returns; 6,188 observations with…
VXX and XIV Returns by Day of the WeekFreeVXX returns are uniformly negative and most negative on Mondays/Tuesdays, while XIV shows the opposite pattern with positive returns largest early week (VXX Feb…
Anomalies by Day of the WeekFreeSentiment-sensitive U.S. stock anomaly returns vary systematically by weekday, with speculative stocks underperforming Mondays and outperforming Fridays (July 1963–Dec 2013; 14 anomalies; descriptive correlational…