
Are target‐date (glidepath) funds that periodically decrease (increase) allocation to stocks (bonds and cash) as the investor ages competitive with alternative strategies? In his February 2013 paper entitled “The Glidepath Illusion: An International Perspective”, Javier Estrada evaluates three alternative types of strategies, all based on a working life of 40 years with annual retirement fund contributions of $1,000 (inflation‐adjusted for a cumulative contribution of $40,000 in real terms):
- Lifecycle strategies with initial stock-bond allocations (in percent) of 100‐0, 90‐10, 80‐20, 70‐30 and 60‐40, and respective final allocations of 0-100, 10‐90, 20‐80, 30‐70 and 40‐60. Allocation adjustments are annual on linear glidepaths.
- Mirror image strategies that start with 0-100, 10‐90, 20‐80, 30‐70 and 40‐60 allocations and end with 100‐0, 90‐10, 80‐20, 70‐30 and 60‐40 allocations.
- Five alternative strategies: fully invested in stocks throughout the 40‐year working life (100×40); fully invested in stocks for the first 20 or 30 years, then shifting annually and linearly out of stocks and into bonds for the remaining 20 or 10 years to end with a 50‐50 stock‐bond allocation (100×20 or 100×30); and, a constant stock-bond allocation of 50‐50 or 60‐40 over 40 years, rebalanced annually.
For each of the World, Europe and 19 developed countries, he generates terminal wealth statistics for 71 overlapping 40-year intervals, the first spanning 1900-1939 and the last spanning 1970-2009. Using real total returns for individual countries (in local currencies adjusted by local inflation) and for the World and Europe (in dollars adjusted by U.S. inflation) during 1900 through 2009, he finds that:
- In general, lifecycle strategies generate lower mean, median and maximum terminal wealth than either their mirror images or the alternative strategies over the sample period.
- While the lifecycle strategies are generally less volatile than the mirror image and alternative strategies, the lifecycle strategies generally produce lower minimum terminal wealth over the sample period.
- In other words, cumulative outperformance of the mirror image and alternative strategies compared to the lifecycle strategies tend to override bad luck over a working lifetime.
The following chart, constructed from data in the paper, summarizes median and minimum real terminal wealth for three lifecycle strategies, three mirror image strategies and three alternative strategies (all as defined above) applied to U.S. stocks and U.S. Treasury bonds over 40-year intervals during 1900 through 2009. Lifecycle strategies generate lower median terminal wealth and similar or lower minimum terminal wealth than the mirror image and alternative strategies.
The most attractive strategy is 100% investment in stocks for all, or much of the early part, of a 40-year working life.
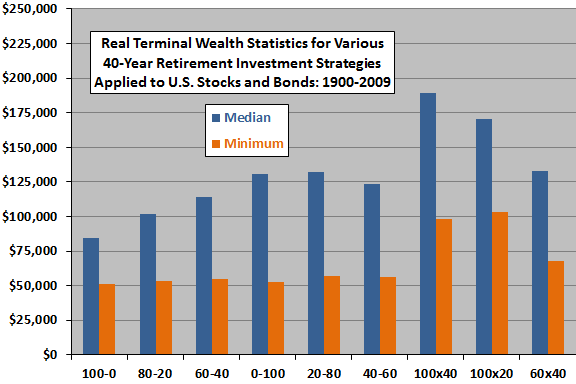
In summary, evidence suggests that lifecycle funds tend to generate lower expected and potential terminal values, without elevating minimum terminal values, compared to their mirror images and to other alternative lifetime stock-bond allocation strategies.
Cautions regarding findings include:
- The study uses returns for indexes rather than tradable assets. Including the costs of creating and maintaining funds as proxies for these indexes would reduce returns.
- Terminal wealth calculations are gross, not net. Including trading frictions associated with annual rebalancing would reduce reported results. In this study, the best-performing strategies have the lowest such trading frictions.
- Use of overlapping measurement intervals overstates sample size and can distort statistics. There are fewer than three independent 40-year intervals in the overall sample, which may not be representative of 40-year intervals over longer periods.
- Results may be sensitive to retirement fund contribution assumptions.
For related research, see “Achilles’ Heel of Pre-determined Lifecycle Funds?” and “Leverage Stock Investments While Young?”.
Frequently Asked Questions
What is a lifecycle or target-date fund and how does its glidepath work?
A lifecycle (target-date) fund is a retirement fund that periodically decreases its allocation to stocks and increases its allocation to bonds and cash as the investor ages, following a glidepath. In the study, allocations adjust annually on a linear path, for example from 100% stocks and 0% bonds at the start of a 40-year working life to 0% stocks and 100% bonds at the end.
Do lifecycle funds outperform other retirement allocation strategies?
Lifecycle funds generally do not outperform alternative strategies. Across 71 overlapping 40-year periods (1900-2009), lifecycle strategies generated lower mean, median and maximum terminal wealth than their mirror images and constant or stock-heavy alternatives. They also tended to produce lower minimum terminal wealth, and the most attractive strategy was 100% stocks for all or much of the early working life.
How is the performance of lifecycle funds tested against alternative strategies over a working life?
Lifecycle strategy performance was tested by simulating a 40-year working life with annual contributions of $1,000 (inflation-adjusted, $40,000 cumulative in real terms) and comparing terminal wealth across strategies. Strategies included lifecycle glidepaths, mirror images, 100% stocks, 100% stocks followed by a shift to 50-50, and constant 50-50 or 60-40 mixes rebalanced annually. Terminal wealth statistics came from 71 overlapping 40-year intervals (1900-1939 through 1970-2009) using real total returns for 19 developed countries, the World and Europe.
How does a lifecycle glidepath compare to a mirror image strategy that starts with bonds and ends with stocks?
A lifecycle glidepath compared to its mirror image strategy, which starts bond-heavy and ends stock-heavy, generally produces lower median, mean and maximum terminal wealth. Lifecycle strategies are generally less volatile, but they also tend to produce lower minimum terminal wealth. The cumulative outperformance of mirror images tends to override bad luck over a working lifetime.
What are the limitations of research showing lifecycle funds underperform?
The research on lifecycle fund underperformance has several caveats: it uses index returns rather than tradable assets, and terminal wealth is gross of fund costs and trading frictions from annual rebalancing. Overlapping 40-year intervals overstate sample size, and fewer than three independent 40-year intervals exist in the 1900-2009 sample, which may not be representative of longer periods. Results may also be sensitive to the assumed retirement contribution pattern.