
Does time series (intrinsic or absolute) momentum work across asset classes prior to the Great Moderation (secular decline in interest rates)? In their August 2016 paper entitled “Trend Following: Equity and Bond Crisis Alpha”, Carl Hamill, Sandy Rattray and Otto Van Hemert test several time series momentum portfolios as applied to groups of bonds, commodities, currencies and equity indexes as far back as 1960. They consider 10 developed country equity indexes, 11 developed country government bond series, 25 agricultural/energy/metal futures series and nine U.S. dollar currency exchange rate series. They calculate return momentum for each asset as the weighted sum of its past monthly returns (up to 11 months) divided by the normalized standard deviation of those monthly returns. They then divide each signal again by volatility and apply a gearing factor to specify a 10% annual volatility target for each holding. Within each of equity index, bond and currency groups, they weight components equally. Within commodities, they weight agriculture, energy and metal sectors equally after weighting individual commodities equally within each sector. They report strategy performance based on excess return, roughly equal to real (inflation-adjusted) return. They commence strategy performance analyses in 1960 to include an extreme bond bear market. Using monthly price series that dovetail futures/forwards from inception with preceding spot (cash) data as available starting as early as January 1950 and as late as April 1990, all through 2015, they find that:
- Over the entire sample period, gross momentum returns based on individual monthly lags are:
- All positive for lags 1 through 12.
- Especially strong for lag 1 and relatively strong for lags 2, 3, 4, 9, 10 and 11.
- Relatively weak for lags 5 through 8 and 12.
- Mostly negative for lags 13 through 24.
- Since 1987 (with fewer assumptions about data), momentum returns based on individual monthly lags are especially strong for lags 1 and 11 and relatively strong for lags 2, 3, 9 and 10.
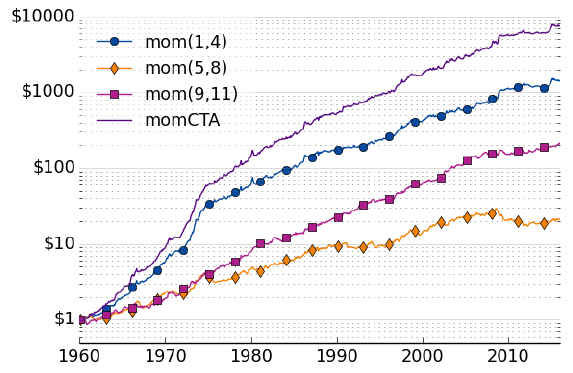
- Gross performance for multi-asset class portfolios with uniform 10% expected annual volatilities depends on momentum strategy specification (see the chart below). Specifically:
- Equally weighted past returns for lags 1 through 4, mom(1,4), is relatively strong.
- Equally weighted returns for lags 5 through 8, mom(5,8), is relatively weak.
- Equally weighted returns for lags 9 through 11, mom(9,11), is relatively strong.
- Weights across lags 1 through 11 selected for optimal tracking of the BTOP50 managed futures index, momCTA, is stronger than the prior three portfolios. These weights concentrate on lags 1, 2 and 3, and monthly returns are highly correlated with those of mom(1,4), suggesting that commodity traders ignore the useful signals from lags 9 through 11.
- All momentum portfolios perform consistently before and after 1985.
- Returns for mom(1,4) and momCTA are positively skewed.
- Performance of the momCTA strategy is particularly strong during both the worst and the best equity and bond markets.
The following chart, taken from the paper, compares on a logarithmic scale gross compounded excess returns of the four multi-asset class momentum portfolios specified above over the entire sample period. Performance is strongest for momCTA, tracked fairly closely by mom(1,4), both consistent with underreaction to news. The steady and relatively attractive performance of mom(9,11) is perhaps partly due to annual seasonality/reporting effects. Gross annualized Sharpe ratios for the four portfolios are, as listed, 1.30, 0.64, 1.12 and 1.56. Restricting the four portfolios to single asset classes shows that bonds drive the outperformance of mom(1,4) relative to mom(9,11).
In summary, evidence indicates that asset class intrinsic momentum effects are consistent before and after 1985, and that effects concentrate in past returns for monthly lags 1, 2, 3, 9, 10 and 11.
Cautions regarding findings include:
- Early data (when there is no futures market) does not include market reactions to trading. Moreover, analyses of some asset classes are unbalanced since class members have different inception dates.
- Reported performance data are gross, not net. Accounting for portfolio reformation frictions would reduce reported returns. Per the authors: “…we ignore transaction costs and fees, which would impact the general profitability… Assuming a two basis point transaction cost for outright trades leads to a reduction in the annualized return of 0.42% for [momCTA]…” However, markets with such frictions are not available over the entire sample period.
- Selection of momCTA weights across lags is in-sample. An investor operating in real time could not know these weights during the sample period.
- Running different versions of the momentum strategy on the same data introduces snooping bias, such that performance of the best version overstates expectations. The intricate weighting of past returns by monthly lag for momCTA introduces considerable latitude for snooping weights. Testing across subperiods mitigates this concern.
- The portfolio construction/implementation process is too complex for many investors, who would bear fees for delegating to an investment manager.
See also related past research on intrinsic momentum across asset classes, including some applied to exchange-traded products.
Frequently Asked Questions
What is time series momentum (intrinsic or absolute momentum) in investing?
Time series momentum, also called intrinsic or absolute momentum, is a strategy that takes positions in an asset based on that asset's own past returns rather than its performance relative to other assets. In the Hamill, Rattray and Van Hemert study, momentum for each asset is the weighted sum of its past monthly returns (up to 11 months) divided by the normalized standard deviation of those returns. The strategy is applied to bonds, commodities, currencies and equity indexes.
Does time series momentum work across asset classes over the long term?
Time series momentum worked across bonds, commodities, currencies and equity indexes over 1960-2015, with gross returns positive for monthly lags 1 through 12. The momCTA portfolio, which concentrates on lags 1, 2 and 3, had the best gross annualized Sharpe ratio at 1.56, versus 1.30 for mom(1,4), 0.64 for mom(5,8) and 1.12 for mom(9,11). Performance was consistent before and after 1985, but these figures are gross of costs and the momCTA weights were optimized in-sample.
How is a multi-asset time series momentum portfolio built and tested?
The study calculates each asset's momentum signal as a weighted sum of past monthly returns (up to 11 months) divided by the normalized standard deviation of those returns, then divides by volatility again and applies a gearing factor to target 10% annual volatility per holding. Assets are equally weighted within equity index, bond and currency groups, and commodities are weighted equally by sector (agriculture, energy, metals) and then equally within each sector. Testing covers 10 equity indexes, 11 government bond series, 25 commodity futures series and nine currency series from 1960 through 2015, using futures data dovetailed with earlier spot data.
How does the momCTA momentum strategy compare with simple equal-weighted momentum strategies like mom(1,4) and mom(9,11)?
The momCTA strategy, with lag weights chosen to track the BTOP50 managed futures index, outperformed the equal-weighted alternatives, with a gross Sharpe ratio of 1.56 versus 1.30 for mom(1,4), 1.12 for mom(9,11) and 0.64 for mom(5,8). MomCTA weights concentrate on lags 1, 2 and 3, and its returns are highly correlated with mom(1,4), suggesting commodity trading advisors overlook the useful signals from lags 9 through 11. Bonds drive the outperformance of mom(1,4) relative to mom(9,11).
What are the limitations and risks of relying on time series momentum backtests?
The reported time series momentum results are gross of transaction costs and fees; the authors estimate a two basis point trading cost would cut momCTA's annualized return by 0.42%. The momCTA lag weights were selected in-sample, so a real-time investor could not have known them, and testing multiple versions on the same data creates snooping bias that overstates the best version's performance. Early data lacks futures-market trading effects, some asset class samples are unbalanced because of different inception dates, and the portfolio construction is too complex for many investors, who would pay fees to delegate it.