
A reader observed: “One of the problems with simple moving average (SMA) crossing rules is the churning from random price movements across the average. Lars Kestner proposes improvements to SMA crossing rules that signal:
- BUY when: (1) the close crosses over an SMA of the highs (rather than the closes); and, (2) the SMA of the closes is greater today than yesterday.
- SELL when the close crosses below an SMA of the lows (rather than the closes).
These rules create a self-adaptive band around the SMA to identify true trends rather then noise, while retaining most of the responsiveness of daily measurements.” Do these buffered SMA crossing rules outperform pure rules that simply buy (sell) on crossovers (crossunders) based on daily closes? To check, we compare the terminal values from pure and buffered rules for a 200-day SMA (SMA200) applied to both the Dow Jones Industrial Average (DJIA) and its exchange traded fund (ETF) proxy, SPDR Dow Jones Industrial Average (DIA). Using daily highs, lows and closes for DJIA since October 1928 and DIA since January 1998, both through early February 2014, and the contemporaneous 3-month Treasury bill yield as the return on cash, we find that:
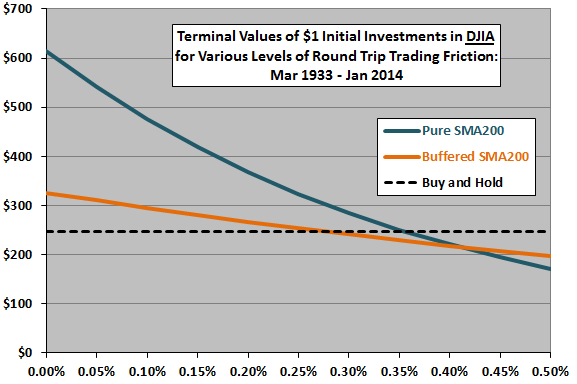
The following chart compares terminal values of $1 initial investments in DJIA using either pure or buffered SMA200 rules for a range of round-trip trading frictions. It also shows the terminal value for a buy-and-hold benchmark. Calculations assume:
- Start each series on 3/15/1933, the first date that both sets of SMA200 rules generate a buy signal.
- End the series on 2/3/2014 when both generate a sell signal.
- It is possible to anticipate signals slightly so that trades are at the close on signal dates (a problematic assumption in trading DJIA via its components over much of the sample period).
- When the buffered SMA200 rules generate consecutive buy or sell signals, use the first signal.
- Trading frictions are constant over the sample period (a problematic assumption for DJIA, since frictions vary considerably over the long sample period).
- The buy-and-hold benchmark bears no trading frictions (somewhat problematic due to changes in DJIA components over time).
- Return on cash is the contemporaneous T-bill yield.
The pure (buffered) SMA200 rules generate 259 (103) DJIA-cash round trip trades and are in stocks 68% (64%) of the time. Buffering thus dramatically suppresses trading while not greatly reducing exposure to DJIA. Results suggest that:
- Pure SMA200 rules outperform buffered rules for round trip trading frictions up to roughly 0.4% of portfolio value.
- Pure (buffered) SMA200 rules outperform the buy-and-hold benchmark for round trip trading frictions up to roughly 0.35% (0.30%) of portfolio value.
For a more realistic, but shorter, test we use the directly tradable DIA over its available history.
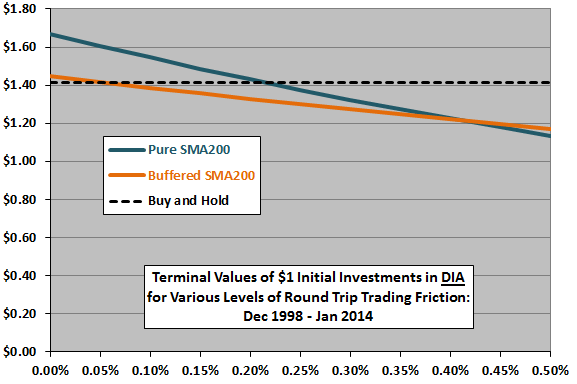
The next chart compares terminal values of $1 initial investments in DIA using either pure or buffered SMA200 rules for a range of round-trip trading frictions. It also shows the terminal value for a buy-and-hold benchmark. Assumption are the same as above, except:
- Start each series on 12/15/1998, the first date that both sets of SMA200 rules generate a buy signal.
- DIA return calculations use dividend-adjusted closes, implying frictionless reinvestment of dividends as accrued.
The pure (buffered) SMA200 rules generate 78 (43) round trip trades and are in stocks 66% (62%) of the time. Buffering thus dramatically suppresses trading while not greatly reducing exposure to DIA. Results suggest that:
- As for DJIA above, pure SMA200 rules outperform buffered rules for round trip trading frictions up to roughly 0.4% of portfolio value.
- Pure (buffered) SMA200 rules outperform the buy-and-hold benchmark for round trip trading frictions up to roughly 0.20% (0.05%) of portfolio value. On this basis, the buffered alternative is not attractive.
In summary, evidence does not support belief that buffered simple moving average crossing signals outperform unbuffered signals for investors bearing low trading frictions.
The above more generally illustrates the interplay among trading frequency, trading frictions and return on cash for simple market timing rules.
Cautions regarding findings include:
- SMA200 rule performance is generally sensitive to the proportion of bull and bear conditions in the sample, and thus to sample start and stop dates.
- As noted, some calculation assumptions are problematic (especially for the DJIA sample).
- Other metrics other than terminal value may be important to investors.
- Other SMA buffering rules may perform differently.
- The specified SMA buffering rules may perform differently for tradable assets other than DIA.
Frequently Asked Questions
What is a buffered simple moving average crossing signal in market timing?
A buffered simple moving average (SMA) crossing signal is a trend-following rule that creates a band around the average to filter out noise. It buys when the close crosses above an SMA of highs and the SMA of closes is higher than yesterday, and sells when the close crosses below an SMA of lows. A pure SMA rule instead buys or sells whenever the daily close crosses the SMA of closes.
Do buffered SMA crossing rules outperform pure SMA crossing rules?
Buffered SMA200 crossing rules do not outperform pure SMA200 rules for investors facing low trading frictions. In tests on the Dow Jones Industrial Average (1933-2014) and the DIA ETF (1998-2014), pure rules beat buffered rules for round-trip frictions up to roughly 0.4% of portfolio value. The evidence therefore does not support the belief that buffering improves results at low trading costs.
How do you test pure versus buffered 200-day moving average timing rules?
The test compares terminal values of $1 invested using pure and buffered SMA200 rules across a range of round-trip trading frictions, with a buy-and-hold benchmark. It uses daily DJIA data starting 3/15/1933 and DIA data starting 12/15/1998, both through early February 2014, with the 3-month Treasury bill yield as the return on cash. DIA calculations use dividend-adjusted closes, and consecutive buffered signals use the first signal.
How do SMA200 timing rules compare to buy-and-hold after trading costs?
SMA200 timing rules beat buy-and-hold only when trading frictions are low. For DJIA, pure (buffered) rules outperformed buy-and-hold for round-trip frictions up to roughly 0.35% (0.30%) of portfolio value. For DIA, the thresholds were roughly 0.20% (0.05%), making the buffered rule unattractive on this basis.
What are the limitations of backtesting SMA200 crossing rules?
SMA200 rule performance is sensitive to the mix of bull and bear conditions in the sample, and therefore to start and stop dates. Some assumptions are problematic, especially for DJIA, including constant trading frictions over a long period, trades at signal-date closes, and changing index components. Metrics other than terminal value may matter, and other buffering rules or other tradable assets may perform differently.