
Conventional wisdom holds that: (1) risk begets reward; and, (2) volatility is a manifestation of risk. Exceptionally high volatility in individual stock prices should, therefore, indicate future excess returns in those stocks. In their May 2006 paper entitled “The Relation between Time-Series and Cross-Sectional Effects of Idiosyncratic Variance on Stock Returns in G7 Countries”, Hui Guo and Robert Savickas investigate why the realized idiosyncratic volatility (beta) of individual stocks correlates negatively with future returns — why there is a penalty instead of a reward for this apparent risk. Using two sets of U.S. data (1926-2005 and 1963-2005) and one set of international data (1973-2003), they conclude that:
- Stocks with high realized idiosyncratic volatility do tend to underperform, both in the U.S. and internationally.
- Overall stock market volatility consistently relates positively to the returns of various portfolios of small, medium-sized and large market capitalizations. However, average idiosyncratic volatility relates negatively to these same returns.
- The idiosyncratic volatility premium relates strongly to the value premium. Value stocks tend to have low volatilities, while growth stocks tend to have high volatilities. (See the figure below.)
- The underlying cause of the volatility premium and the value premium is sensitivity to discount rate shocks. Volatile (growth) stocks are very sensitive to discount rate shocks, while quiet (value) stocks are not.
The following figures, taken from the paper, show two different ways of predicting the returns of the same 25 portfolios. The top figure shows the results of predictions based on the value (book-to-market) premium, with portfolios ranking higher in value outperforming those ranking lower in value. The bottom figure shows the results of predictions based on the volatility premium, with portfolios ranking higher in average idiosyncratic volatility outperforming those ranking lower in volatility. The very similar results confirm a close, negative relationship between value and volatility. Value stocks tend to be less volatile than growth stocks.
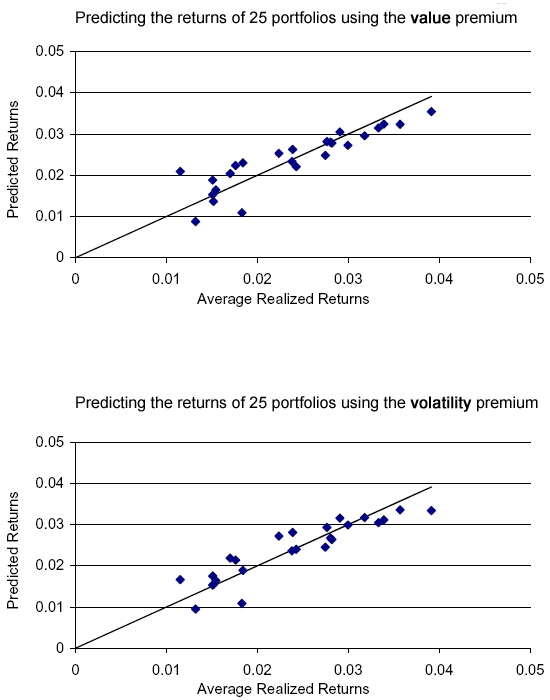
In summary, the idiosyncratic volatility premium is closely related to the value premium, with low volatility and high value stocks tending to outperform. Insensitivity to discount rate (inflation, interest rates) shocks is the common underlying factor.
Frequently Asked Questions
What is idiosyncratic volatility in stocks?
Idiosyncratic volatility is the portion of an individual stock's price variability that is specific to that stock rather than driven by the overall market. In the Guo and Savickas study, realized idiosyncratic volatility is measured at the individual-stock level and used to examine whether it predicts future returns.
Do highly volatile stocks underperform the market?
Stocks with high realized idiosyncratic volatility tend to underperform, both in the U.S. and internationally. This finding comes from portfolio sorts using U.S. data (1926-2005 and 1963-2005) and international G7 data (1973-2003). It contradicts the conventional view that higher risk should bring higher returns.
How is the idiosyncratic volatility premium tested using portfolios?
The idiosyncratic volatility premium is tested by sorting stocks into portfolios and comparing returns across them. Guo and Savickas used 25 portfolios of small, medium-sized and large capitalization stocks, ranked by average idiosyncratic volatility and separately by book-to-market value, and compared the two sets of results. Overall market volatility related positively to portfolio returns, while average idiosyncratic volatility related negatively.
Is the low volatility effect the same as the value premium?
The idiosyncratic volatility premium is closely related to the value premium but is measured differently. Value stocks tend to have low volatility and growth stocks high volatility, and rankings of the same 25 portfolios by book-to-market and by volatility gave very similar results. The authors attribute both to a common factor: sensitivity to discount rate shocks such as inflation and interest rate changes, to which volatile growth stocks are highly sensitive and quiet value stocks are not.
What are the limitations of using idiosyncratic volatility to predict stock returns?
The idiosyncratic volatility effect is not independent of other known return drivers, since it is closely tied to the value premium and to sensitivity to discount rate shocks. The findings rest on realized volatility and historical portfolio sorts (U.S. 1926-2005 and 1963-2005; international 1973-2003), so they describe past average relationships rather than guaranteed future outcomes. The article also shows the relationship is negative for idiosyncratic volatility but positive for overall market volatility, so the two should not be conflated.