
Are popular exchange-traded products (ETP) such as VXX (iPath S&P 500 VIX Short Term Futures) and VXZ (iPath S&P 500 VIX Mid-Term Futures), designed to track specific S&P 500 VIX futures constant maturity index series, good hedges for stock portfolios? In their June 2012 paper entitled “Are VIX Futures ETPs Effective Hedges?”, Geng Deng, Craig McCann and Olivia Wang investigate whether these ETPs effectively hedge basic U.S. stock portfolios or exchange-traded funds (ETF) that leverage U.S. stock market indexes. Because the ETPs are only very recently available, they use the one-month (SPVXSP) and five-month (SPVXMP) S&P 500 VIX futures constant maturity indexes as proxies for them. They examine the hedging effectiveness of these indexes for five stock portfolios: 100% SPDR S&P 500 (SPY); 100% Vanguard Total Stock Market Index Fund (VTSMX); 80% VTSMX and 20% Vanguard Total Bond Market Index Fund (VBMFX); 60% VTSMX and 40% VBMFX; and, 40% VTSMX and 60% VBMFX. They also examine the hedging effectiveness of these indexes for three 2x-leveraged exchange-traded funds (ETF): ProShares Ultra S&P500 (SSO); ProShares Ultra QQQ (QLD); and, ProShares Ultra Dow30 (DDM). They compute optimal hedge ratios using consecutive (non-overlapping) 26-week lagged regressions of weekly total returns of each portfolio/ETF versus weekly returns of the hedging instrument. Using weekly data for all portfolio funds and VIX futures indexes since December 2005, and for leveraged ETFs since late July 2006, all through mid-April 2012, they find that:
- Over the sample period since December 2005, the correlation of weekly returns between SPY and SPVXSP (SPVXMP), tracked by VXX (VXZ), is -0.74 (-0.68). The average annual return of SPVXSP (SPVXMP) is -21.3% (6.4%).
- VIX futures indexes applied as hedges do not significantly reduce the volatility of either stock portfolios or leveraged ETFs.
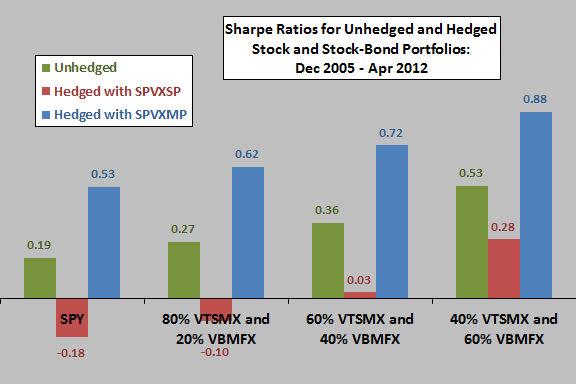
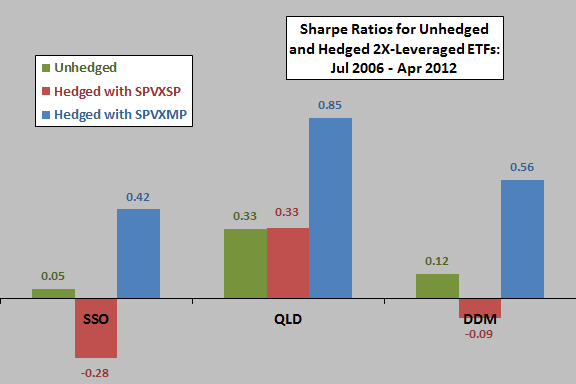
- Short-term VIX futures indexes applied as hedges substantially reduce returns and Sharpe ratios of stock portfolios and leveraged ETFs because of the usually negative roll yield incurred while maintaining constant maturity (see the charts below).
- Medium-term VIX futures indexes, with less negative roll yields, boost returns and Sharpe ratios when applied as hedges for stock portfolios and leveraged ETFs (see the charts below).
The following chart, constructed from data in the paper, summarizes Sharpe ratios for unhedged stock (SPY) and several stock-bond (VTSMX-VBMFX in different proportions) portfolios, and for these same portfolios hedged with either SPVXSP or SPVXMP, over the available sample period. Hedge ratios derive from 26-week lagged regressions of weekly portfolio returns versus hedging instrument weekly returns.
Results indicate that medium-term (short-term) VIX futures indexes are (are not) effective diversifiers for stocks portfolios over this period.
The next chart, also constructed from data in the paper, summarizes Sharpe ratios for unhedged leveraged stock ETFs, and for these same ETFs hedged with either SPVXSP or SPVXMP, over the available sample period. Hedge ratios again derive from 26-week lagged regressions of weekly portfolio returns versus hedging instrument weekly returns.
Results indicate that medium-term (short-term) VIX futures indexes are (are not) effective diversifiers for leveraged ETFs over this period.
In summary, evidence indicates that exchange-traded products that track medium-term VIX futures indexes (such as VXZ) may be effective diversifiers for stock portfolios and leveraged stock ETFs, but those that track short-term VIX futures indexes (such as VXX) are not.
Cautions regarding findings include:
- As noted in the paper, the sample periods (which involve just a few VIX regimes, including the very unusual 2008 financial crisis) may not be representative of long-term interactions between stocks and VIX futures indexes.
- Investors may not be able to achieve reported results due to roll trading frictions and fund management fees included in VXX and VXZ (plus minor frictions from adjusting hedge size every six months).
- Consideration of multiple portfolios and two hedging instruments introduces data snooping bias, such that the best-performing historical combination likely overstates future performance.
See the closely related “Diversification with VIX Futures and Related ETNs”. See also “Simple Tests of VXX as Diversifier” and “Simple Tests of VXZ as Diversifier” for context of multi-asset class portfolios.
Frequently Asked Questions
What are VIX futures ETPs like VXX and VXZ?
VIX futures ETPs such as VXX (iPath S&P 500 VIX Short Term Futures) and VXZ (iPath S&P 500 VIX Mid-Term Futures) are exchange-traded products designed to track S&P 500 VIX futures constant maturity index series. VXX tracks a one-month constant maturity index (proxy SPVXSP), while VXZ tracks a five-month index (proxy SPVXMP). Investors use them as potential hedges or diversifiers for stock portfolios.
Are VIX futures ETPs effective hedges for stock portfolios?
VIX futures ETPs are only partly effective as hedges: medium-term products tracking indexes like VXZ's boosted returns and Sharpe ratios of stock portfolios and leveraged ETFs, while short-term products like VXX's reduced them (December 2005 to mid-April 2012). Neither type significantly reduced portfolio volatility. Short-term indexes averaged -21.3% annual return versus 6.4% for medium-term indexes.
How is the hedging effectiveness of VIX futures indexes tested?
Hedging effectiveness of VIX futures indexes was tested by computing optimal hedge ratios from consecutive, non-overlapping 26-week lagged regressions of weekly total returns of each portfolio against weekly returns of the hedging instrument. Because the ETPs were new, the researchers used the one-month (SPVXSP) and five-month (SPVXMP) VIX futures indexes as proxies. They tested five stock/bond portfolios and three 2x-leveraged ETFs (SSO, QLD, DDM) using weekly data through mid-April 2012.
Why do short-term VIX futures like VXX hedge worse than medium-term VIX futures like VXZ?
Short-term VIX futures indexes such as the one tracked by VXX hedge worse than medium-term ones such as VXZ's because of larger negative roll yield incurred while maintaining constant maturity. Although SPY's weekly return correlation was stronger with the short-term index (-0.74) than the medium-term index (-0.68), the short-term index's roll costs substantially reduced returns and Sharpe ratios. The medium-term index's less negative roll yield instead boosted them.
What are the limitations of using VIX futures ETPs to hedge stock portfolios?
The findings on VIX futures ETPs have several caveats: the sample period covers only a few VIX regimes, including the unusual 2008 financial crisis, and may not be representative long term. Investors may not achieve the reported results because of roll trading frictions, fund management fees in VXX and VXZ, and costs of adjusting hedge size every six months. Testing multiple portfolios and two hedging instruments also introduces data snooping bias, so the best historical combination likely overstates future performance.