
Is there a way to predict when beta anomaly arbitrage (long low-beta stocks and short high-beta stocks will work? In the August 2015 version of their paper entitled “The Booms and Busts of Beta Arbitrage”, Shiyang Huang, Dong Lou and Christopher Polk investigate the power of a metric that measures beta arbitrage activity to predict associated returns. They measure beta via regressions of daily stock returns over the past 12 months versus daily market returns (contemporaneous and five lags to smooth unrelated effects). Each month, they rank stocks by beta and reform a hedge portfolio that is long (short) the value-weighted tenth, or decile, of stocks in the lowest (highest) betas. They measure beta arbitrage activity as the average pairwise correlation of weekly three-factor alphas (adjusting for market, size and book-to-market factors) of stocks in the lowest beta decile over the past 52 weeks. They then measure average hedge portfolio alphas for different ranges (ranked fifths, or quintiles) of beta arbitrage activity by month over long holding intervals. Using daily returns and other data for a broad sample of U.S. common stocks during 1970 through 2010, they find that:
- The specified measure of beta arbitrage activity generally agrees with those based on institutional and hedge fund holdings, but appears to capture additional information.
- When beta arbitrage activity is low (bottom 20% of values):
- Beta hedge portfolio alpha takes two or three years to develop.
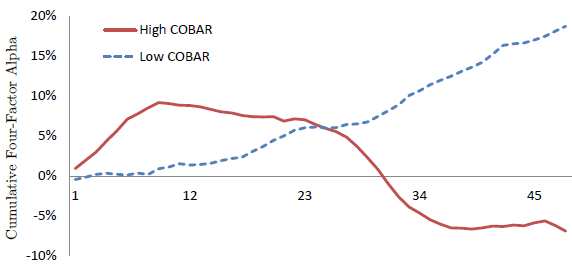
- However, during the third year, average gross monthly alpha is 0.85%.
- When beta arbitrage activity is high (top 20% of values):
- Beta hedge portfolio alpha develops quickly. During the first six months, average gross monthly alpha is 1.56%.
- However, strategy alpha overshoots and then reverts, perhaps due to strategy crowding. Reversion is strongest during the third year, with average gross monthly alpha -0.74%.
- Adding the momentum factor to alpha calculations has little effect on beta hedge portfolio alpha (see the chart below).
- Variation of beta arbitrage strategy performance is particularly strong for stocks of firms with high financial leverage.
- Results are robust to use of monthly returns and to other beta calculation intervals.
The following chart, taken from the paper, tracks four-factor alpha (adjusting for market, size, book-to-market and momentum factors) for the beta hedge portfolio during the 20% of observations with the highest (red line) and lowest (dashed blue line) beta arbitrage activity (termed COBAR in the paper). When beta arbitrage activity is low, alpha is slow to develop, is strongest during year three and does not revert. When beta arbitrage activity is high, alpha is quick to develop but apparently overshoots, resulting in reversion that is particularly strong in year three.
In summary, evidence indicates that portfolios that are long low-beta stocks and short high-beta stocks tend to have strong (weak) near-term performance when measurable beta arbitrage activity is relatively high (low).
Cautions regarding findings include:
- Reported alphas are gross, not net. Accounting for monthly trading frictions and continuous shorting costs would lower alphas. Moreover:
- Trading frictions and shorting costs may vary with level of arbitrage activity, thereby affecting findings.
- Shorting may not be feasible for some stocks that are very difficult to borrow.
- Most investors would have to delegate portfolio management, and thereby bear fees that reduce alpha.
- Variation in beta arbitrage strategy alphas is not systematic across arbitrage activity quintiles, suggesting tail effects rather than a consistent relationship.
- Test measurements are fairly complex, suggesting potential for data snooping bias in tested parameter settings.
Frequently Asked Questions
What is beta arbitrage in investing?
Beta arbitrage is a strategy that goes long low-beta stocks and short high-beta stocks to exploit the beta anomaly, where low-beta stocks have earned higher risk-adjusted returns than high-beta stocks. In the study, beta is measured from regressions of daily stock returns against market returns over the past 12 months, and the hedge portfolio uses the value-weighted lowest and highest beta deciles.
Does beta arbitrage activity predict when a low-beta minus high-beta strategy will work?
Beta arbitrage activity does help predict low-beta minus high-beta performance, based on U.S. stock data from 1970 through 2010. When activity is high (top 20% of values), the hedge portfolio earned 1.56% average gross monthly alpha in the first six months but reverted to -0.74% in year three. When activity is low (bottom 20%), alpha developed slowly, reaching 0.85% monthly in year three without reverting.
How is beta arbitrage activity measured?
Beta arbitrage activity is measured as the average pairwise correlation of weekly three-factor alphas (adjusted for market, size and book-to-market factors) among stocks in the lowest beta decile over the past 52 weeks. The researchers then compute average hedge portfolio alphas for each quintile of this measure over long holding periods. Beta itself comes from regressing daily stock returns on contemporaneous and five lagged daily market returns over 12 months.
Does the beta arbitrage activity measure capture the same thing as hedge fund and institutional holdings data?
The beta arbitrage activity measure generally agrees with measures based on institutional and hedge fund holdings, but it is not identical to them. The study finds it appears to capture additional information beyond those holdings-based measures. Adding the momentum factor to alpha calculations had little effect on the hedge portfolio's alpha.
What are the limitations of trading a low-beta minus high-beta strategy based on arbitrage activity?
The reported alphas of the low-beta minus high-beta strategy are gross, so trading frictions and continuous shorting costs would reduce them, and shorting may be infeasible for hard-to-borrow stocks. Most investors would also bear fees from delegating management, and alpha variation across arbitrage activity quintiles is not systematic, suggesting tail effects rather than a consistent relationship. The measurements are also complex, raising the risk of data snooping bias in the tested parameter settings.