
Does the lunar cycle still (since our last look seven years ago) affect the behavior of investors/traders, and thereby influence stock returns? In the August 2001 version of their paper entitled “Lunar Cycle Effects in Stock Returns” Ilia Dichev and Troy Janes conclude that: “returns in the 15 days around new moon dates are about double the returns in the 15 days around full moon dates. This pattern of returns is pervasive; we find it for all major U.S. stock indexes over the last 100 years and for nearly all major stock indexes of 24 other countries over the last 30 years.” To refine this conclusion and test recent data, we examine U.S. stock returns around new and full moons since 1990. When the date of a new or full moon falls on a non-trading day, we assign it to the nearest trading day. Using dates for new and full moons for January 1990 through August 2018 as listed by the U.S. Naval Observatory (355 full and 354 new moons) and contemporaneous daily closing prices for the S&P 500 Index, we find that:
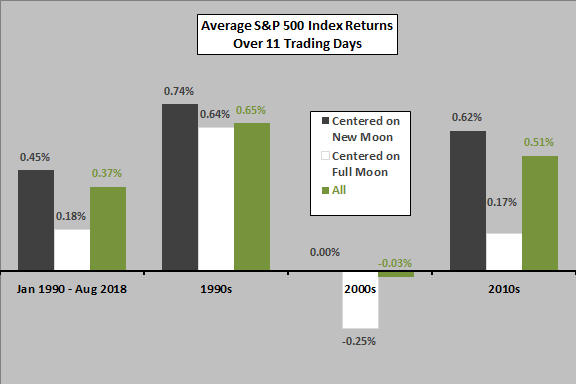
The following chart summarizes average S&P 500 Index returns for the 11 trading days (about half a month) for all days and for days centered on new moons or on full moons over the full sample period and by decade (through August 2018 for 2010s).
Results are in rough agreement with the conclusion of the study cited above, with intervals centered on new moons consistently outperforming those centered on full moons.
The standard deviation of 11-day returns over the full sample period is 2.94% (3.41%) centered on new (full) moons, large compared to the difference in average returns.
How is the difference in returns around new and full moons distributed?
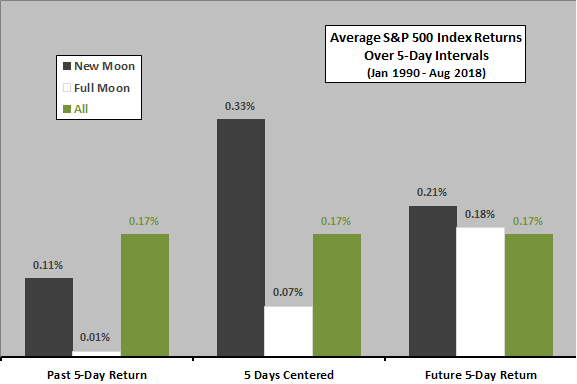
The next chart compares average S&P 500 Index returns over the entire sample period for three intervals relative to new or full moons: (1) the five trading days just before full or new moons; (2) the five trading days centered on new or full moons; and, (3) the five trading days just after new or full moons. Average return for all 5-day intervals is 0.17%.
Notable point are:
- Average outperformance of the interval around new moons comes mostly from returns before and immediately around new moons.
- However, average return just before new moons is below normal.
- Average return just after full moons is normal.
Standard deviations of 5-day returns for these intervals over the full sample period are in the range 2.01%-2.55%, large compared to differences in average returns.
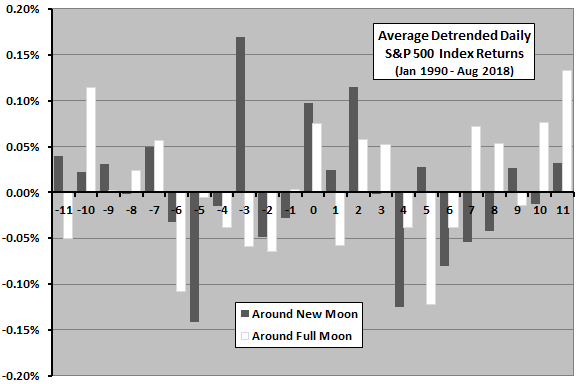
For deeper insight, we look at daily average returns around new and full moons.
The final chart summarizes average daily detrended S&P 500 Index returns from 11 trading days before to 11 trading days after new moons and full moons We detrend by subtracting the average daily return for the full sample period (0.04%) from the raw average returns for each trading day in the intervals tested. Lack of systematic variation in daily detrended returns undermines belief in the lunar cycle as the explanation of new-full moon difference in average returns.
Physicist Charles Pennington employs a different approach using a Fourier transform, concluding that lunar cycle effects on SPDR S&P 500 (SPY) are, if they exist, very small.
In summary, evidence from simple tests confirms that the U.S. stock market since 1990 performs better on average around new moons than full moons, but the effect is “lumpy.”
Cautions regarding findings (as noted above) include:
- As noted, levels of outperformance are small compared to return variability, so trading them is very risky.
- Levels of outperformance are not convincingly consistent across subperiods and daily returns.
Frequently Asked Questions
What is the lunar cycle effect in stock returns?
The lunar cycle effect in stock returns is the hypothesis that the moon's phases influence investor behavior and thereby stock performance, with returns differing around new moons and full moons. A study by Ilia Dichev and Troy Janes found returns in the 15 days around new moons were about double those around full moons across major U.S. indexes over 100 years and in 24 other countries over 30 years.
Does the lunar cycle predict S&P 500 returns?
The lunar cycle shows a modest pattern in S&P 500 returns, with 11-day intervals centered on new moons outperforming those centered on full moons from January 1990 through August 2018 (354 new and 355 full moons). However, the effect is small relative to return variability and not convincingly consistent across subperiods, so it is not a reliable predictor.
How are stock returns around new and full moons tested?
Stock returns around new and full moons are tested by taking new and full moon dates from the U.S. Naval Observatory and averaging S&P 500 returns over intervals centered on those dates, such as 11 trading days or 5-day windows before, around and after. Moon dates falling on non-trading days are assigned to the nearest trading day, and daily returns are detrended by subtracting the full-sample average daily return of 0.04%.
Is the new moon effect on stocks driven by the lunar cycle itself or by something else?
The evidence does not clearly attribute the new-versus-full-moon return difference to the lunar cycle itself, since daily detrended S&P 500 returns show no systematic variation around moon dates. Outperformance around new moons comes mostly from returns before and immediately around them, while returns just after full moons are normal. Physicist Charles Pennington's Fourier transform analysis likewise concludes that lunar effects on SPY, if they exist, are very small.
What are the risks and limitations of trading on moon phases?
Trading on moon phases is very risky because the outperformance of new moon intervals is small compared to return variability; the standard deviation of 11-day returns is 2.94% around new moons and 3.41% around full moons. The differences are also not convincingly consistent across subperiods and daily returns, and the average return just before new moons is below normal. The pattern is described as 'lumpy' rather than systematic.