
Do stock prices move systematically at the turn of calendar months? In the July 2006 draft of their paper entitled “Equity Returns at the Turn of the Month”, Wei Xu and John McConnell examine equity returns from the beginning the last trading day of one month through the first three trading days of the next month. Using daily returns for a broad range of stocks across exchanges over the period 1926-2005 (with focus on the segment 1987-2005), they conclude that:
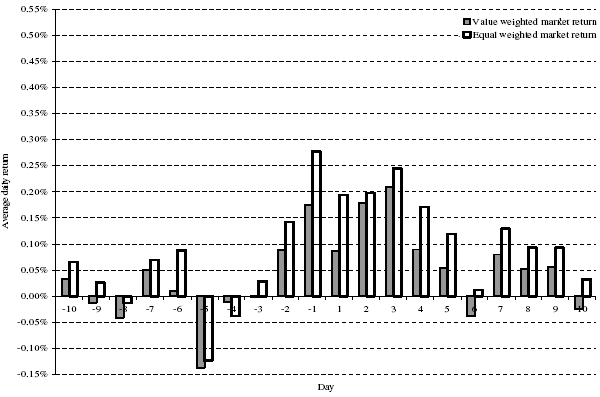
- All excess market returns occur during a four-day turn-of-the-month interval. Since the beginning of 1987, the average daily value-weighted (equal-weighted) excess market return during the turn of the month is 0.14% (0.24%), compared to -0.01% (0.04%) during the other 16 trading days of the month.
- Return variability (standard deviation) is no higher during the turn of the month than during other days.
- The turn-of-the-month effect is not confined to small or low-priced stocks, although small-capitalization stocks have especially high returns on the last day of the trading month.
- The turn-of-the-month effect is not confined to turns of the year (December to January) or turns of calendar quarters.
- The turn-of-the-month effect is not confined to U.S. markets. Stock markets in 30 of 34 other countries examined also exhibit the effect.
- Neither Treasury instruments nor corporate bonds exhibit significant turn-of-the-month effects.
- There is no good explanation for the turn-of-the-month effect. Neither “payday” nor risk-factor nor behavioral explanations work. Neither trading volume nor net flows to mutual funds are higher during the turn of the month than during other days.
The following chart, taken from the paper, shows the average daily value-weighted and equal-weighted market returns for the last 10 trading days and the first 10 trading days of the month over the period 1987-2005. Day -1 is the last trading day of the month. Day +1 is the first trading day of the month. The chart demonstrates the concentration of returns around the turn of the month.

The next chart, also from the paper, shows the same results over the longer preceding period of 1926-1986. The chart demonstrates that the turn-of-the-month effect is long-standing.
In summary, the significant concentration of excess stock market returns around the turns of calendar months is a long-standing and persistent effect.
Frequently Asked Questions
What is the turn-of-the-month effect in the stock market?
The turn-of-the-month effect is the tendency for stock market returns to concentrate in a four-day window, running from the last trading day of one month through the first three trading days of the next. In a study of broad U.S. stocks since 1987, the average daily value-weighted excess market return in this window was 0.14%, versus -0.01% on the other 16 trading days of the month.
Does the turn of the month predict higher stock returns?
Yes, the turn-of-the-month interval captured all excess U.S. stock market returns in the 1987-2005 study period. Average daily value-weighted (equal-weighted) excess returns were 0.14% (0.24%) in the four-day window versus -0.01% (0.04%) on other days. The effect also appears in the 1926-1986 period, indicating it is long-standing and persistent.
How is the turn-of-the-month effect measured and tested?
The turn-of-the-month effect is measured by comparing average daily excess market returns during the last trading day of a month plus the first three trading days of the next month against returns on the remaining trading days. Xu and McConnell used daily returns for a broad range of stocks across exchanges over 1926-2005, focusing on 1987-2005, and examined both value-weighted and equal-weighted returns. They also checked small versus large stocks, year and quarter turns, 34 other countries, and Treasury and corporate bonds.
Is the turn-of-the-month effect the same as the January effect or a year-end effect?
No, the turn-of-the-month effect is not confined to the December-to-January turn of the year or to calendar quarter turns, so it differs from a year-end or January-specific pattern. It also is not limited to small or low-priced stocks, though small-cap stocks show especially high returns on the last trading day of the month. The effect appears in stock markets of 30 of 34 other countries examined, but not significantly in Treasury instruments or corporate bonds.
Why is the turn-of-the-month effect hard to explain or exploit?
The turn-of-the-month effect has no good explanation: payday, risk-factor, and behavioral explanations all fail to account for it in the Xu and McConnell study. Return variability is no higher in the window, and neither trading volume nor net mutual fund flows are higher than on other days, so the usual drivers do not appear to explain it. The findings are based on a 2006 draft paper using data through 2005.