
How do moving averages work for timing asset prices, and how do different kinds of moving averages work differently? In his October 2016 paper entitled “Moving Averages for Market Timing”, Valeriy Zakamulin presents in three chapters: (1) financial series trend detection and turning point identification using moving averages; (2) the mathematics and properties of moving averages, with focus on smoothness and lag time; and, (3) types of moving averages, including regular moving averages, moving averages of moving averages and mixed moving averages that suppress lag time, with focus on differences in smoothness and lag time. Based on mathematical analyses, he concludes that:
- The longer the averaging window, the smoother the moving average (the better the removal of noise and avoidance of spurious signals), but the greater the lag time between an actual change in price trend and the associated moving average turning point. The optimal averaging window is a trade-off between smoothness and lag time.
- Moving average types differ in the way they weight past prices, and differences in weighting approaches (for a given averaging window) produce differences in smoothness and lag time. In general:
- The more even the weighting of past prices, the smoother the moving average.
- The stronger the weighting of the most recent past prices, the smaller the lag time. Smoothness and lag time therefore relate inversely.
- Moving averages that overweight the most recent prices provide a more efficient trade-off between smoothness and lag time than does equal weighting (see the chart below). However, this superior efficiency may not translate into a significant advantage in practical applications.
The following chart, taken from the paper, summarizes relationships between smoothness and turning point identification lag time for four kinds of moving averages:
- SMA – Simple Moving Average (past prices weighted equally).
- LMA – Linear Moving Average (most recent past prices weighted linearly higher than older past prices).
- EMA – Exponential Moving Average (most recent past prices weighted exponentially higher than older past prices), with information in older prices discarded more quickly than with LMA.
- ZLEMA – Zero Lag Exponential Moving Average, a linear combination of two EMAs that has negative weights on older past prices.
Results suggest that EMA offers the best trade-off between smoothness and lag time in turning point identi cation, followed by LMA and then SMA. ZLEMA offers the worst trade-off, despite its construction to suppress lag time.
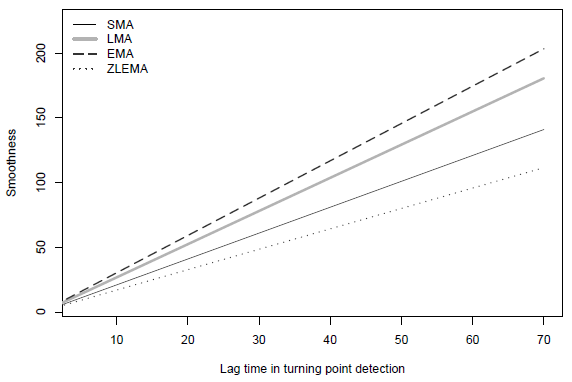
In summary, theory suggests that EMA may have an inherent advantage over LMA and SMA with respect to the trade-off between moving average smoothness and lag time between actual trend change and moving average turning point.
Cautions regarding findings include:
- The paper is theoretical in nature and does not include any applications of concepts to asset timing. See the research listed below for practical applications.
- As noted in the paper, the theoretical superiority of EMA over LMA and SMA may not translate into material practical superiority.
For related research on the use of moving averages for market timing by the same author, see:
- Challenging SMA Effectiveness for Stocks
- Long-run Moving Average Horse Race for Timing the U.S. Stock Market
- Best Moving Average Weighting Scheme for Market Timing?
- Market Timing with Moving Averages Over the Very Long Run
- Net Performance of SMA and Intrinsic Momentum Timing Strategies
Frequently Asked Questions
What is a moving average and how is it used for market timing?
A moving average is an average of an asset's past prices over a chosen window, used to identify price trends and the turning points that signal a change in trend. In market timing, a turning point in the moving average serves as a signal to buy or sell. Moving average types differ in how they weight past prices, such as simple, linear, exponential, and zero lag exponential.
Which type of moving average offers the best trade-off between smoothness and lag time?
The exponential moving average (EMA) offers the best trade-off between smoothness and lag time in turning point identification, according to Valeriy Zakamulin's October 2016 mathematical analysis. It is followed by the linear moving average (LMA) and then the simple moving average (SMA). The zero lag exponential moving average (ZLEMA) offers the worst trade-off despite being built to suppress lag.
How does the length of a moving average window affect smoothness and lag?
A longer moving average window makes the average smoother, removing more noise and avoiding spurious signals, but increases the lag between an actual price trend change and the moving average turning point. The optimal window is therefore a trade-off between smoothness and lag time. For a given window, more even weighting of past prices yields greater smoothness, while heavier weighting of recent prices yields less lag.
How do simple, linear, and exponential moving averages differ?
Simple moving averages (SMA) weight past prices equally, linear moving averages (LMA) weight recent prices linearly higher than older ones, and exponential moving averages (EMA) weight recent prices exponentially higher while discarding older information more quickly than LMA. Equal weighting gives more smoothness, while stronger recent weighting gives less lag time. Overweighting recent prices gives a more efficient smoothness-lag trade-off than equal weighting.
Does the theoretical advantage of exponential moving averages hold up in practical market timing?
Not necessarily: the theoretical superiority of the exponential moving average (EMA) over the linear and simple moving averages may not translate into a significant practical advantage, as the paper itself notes. The paper is purely theoretical, based on mathematical analysis, and includes no applications of the concepts to actual asset timing. Its findings therefore do not establish that EMA-based timing strategies outperform in practice.